

Sofeast’s team continues to monitor the cost evolution of key raw materials in China, helping importers and manufacturers stay informed.
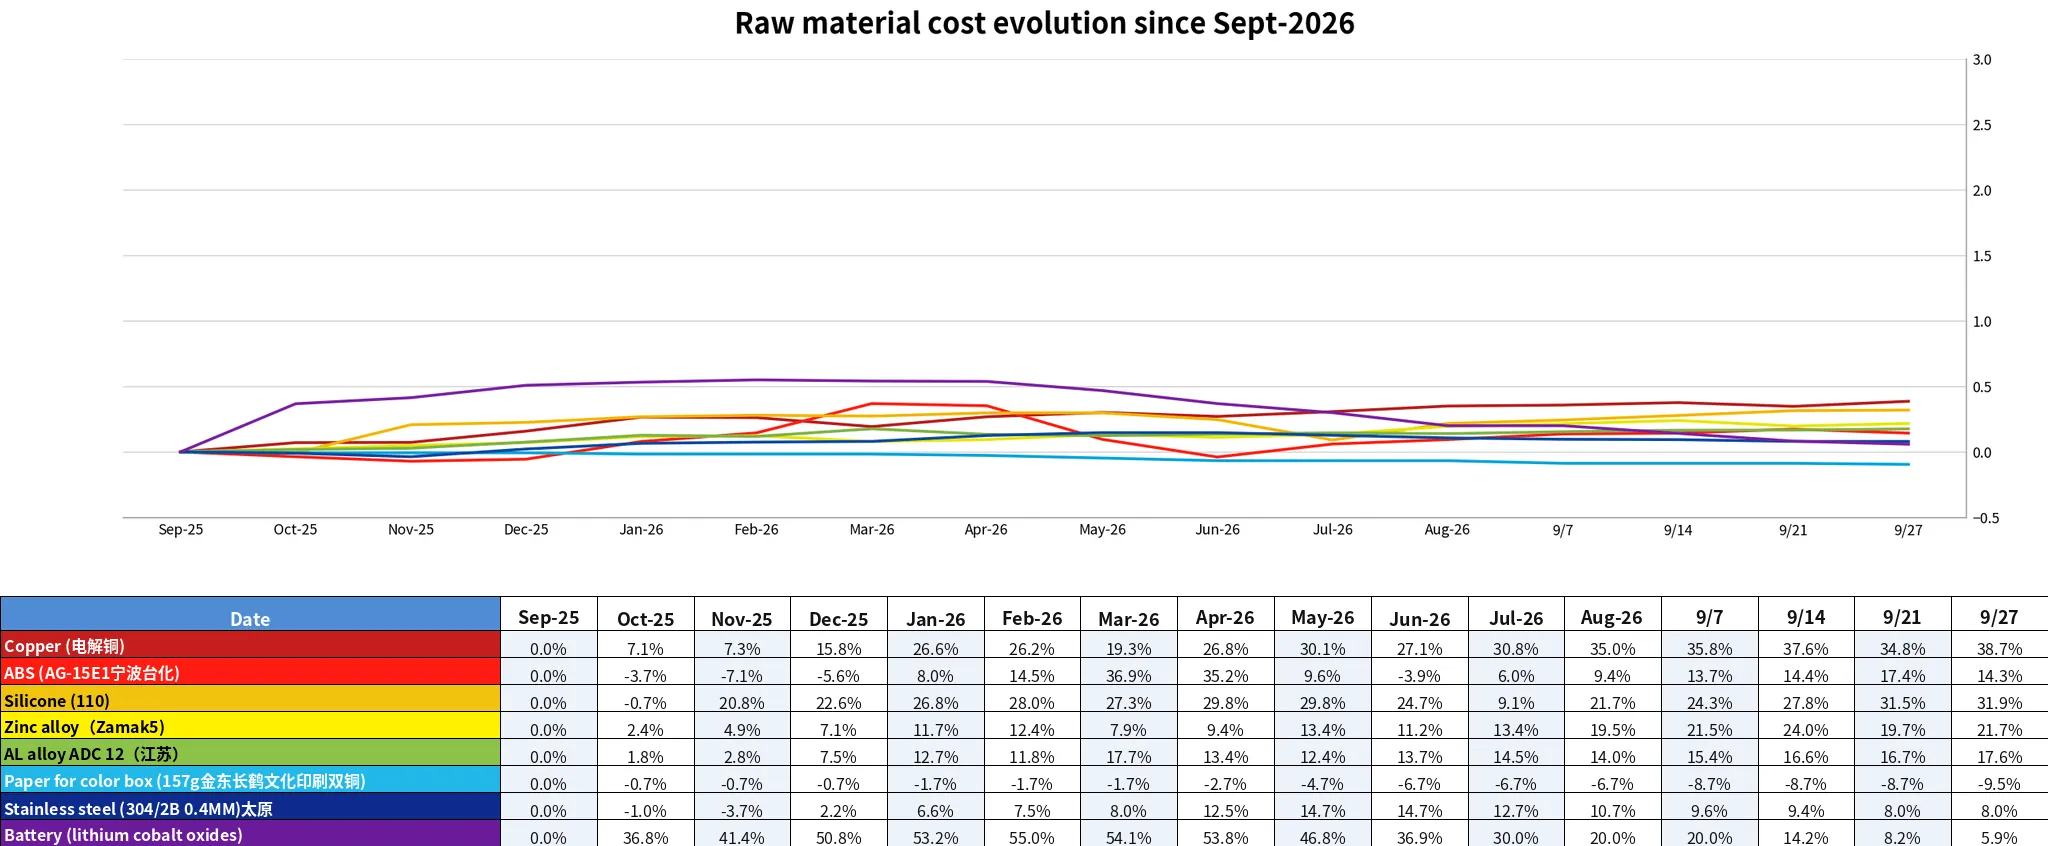
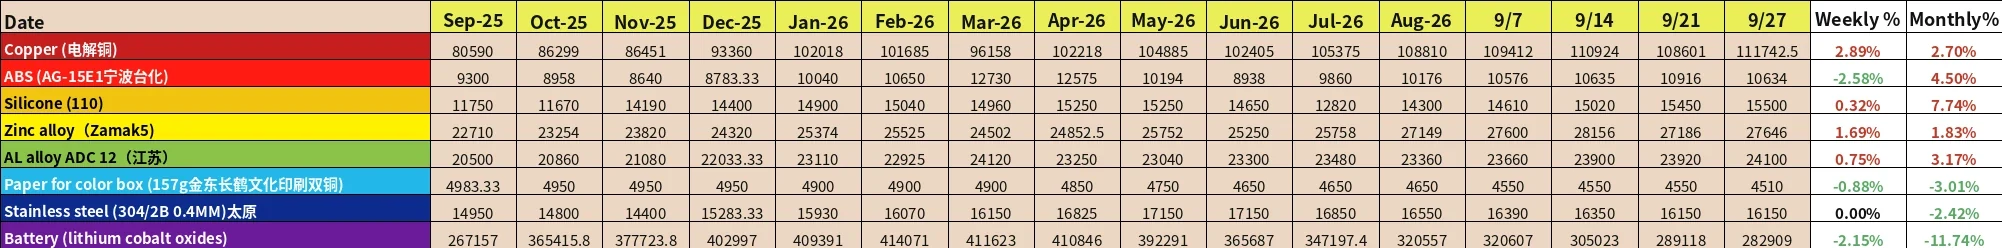
This latest update from the market analysts we work with reflects changes in RMB costs and percentages through September 27, 2026.
Click the charts to expand them.
Monthly China Raw Material Cost Changes – September 2026
The market remained mixed in September, although several conventional manufacturing materials we track moved higher.
Silicone recorded the largest monthly increase, followed by ABS and aluminum alloy. Copper and zinc alloy also rose.
At the other end of the scale, battery materials continued their significant downward trend, while packaging paper and stainless steel also declined.
Copper – Monthly Change: +2.70%
Copper moved higher during September and recorded a 2.89% increase during the latest week.
- Drivers
Spot copper prices increased as inventories remained low during the traditional peak-demand season, providing support for prices. - Outlook (next month)
Copper prices are expected to remain relatively high into October, although there does not currently appear to be a strong factor that would drive another substantial increase.
ABS (AG-15E1) – Monthly Change: +4.50%
ABS finished September above its August level, although prices fell by 2.58% during the latest week.
- Drivers
The latest decline was influenced by falling crude oil prices and relatively weak ABS market fundamentals. Trading activity also remained subdued. - Outlook (next month)
Upstream prices are expected to remain relatively stable, while ABS suppliers continue to face sales pressure. This may keep ABS prices relatively weak during October.
Silicone (110) – Monthly Change: +7.74%
Silicone recorded the largest monthly increase among the main manufacturing materials tracked in this update, continuing the strong upward movement seen since July.
Prices were much more stable during the latest week, increasing by just 0.32%.
- Drivers
The price of 110 raw silicone rubber stabilized after its recent increases. Manufacturers are still largely fulfilling existing orders, inventories remain relatively low, and some downstream buyers have needed to replenish their raw material stocks. - Outlook (next month)
Raw material prices may stabilize or soften somewhat during October, potentially reducing some of the cost-side support behind silicone’s recent increases.
Zinc Alloy (Zamak 5) – Monthly Change: +1.83%
Zinc alloy prices increased moderately during September, including a further 1.69% rise during the latest week.
- Drivers
Electrolytic zinc prices fluctuated upward during the week, raising the average market price and supporting zinc alloy costs. - Outlook (next month)
Inventory preparation around the holiday period may continue to support zinc prices, which could remain relatively high in the near term. Further movements will depend partly on downstream demand after the holiday period.
Aluminum Alloy (ADC 12, Jiangsu) – Monthly Change: -3.17%
Aluminum alloy prices rose during September and increased by another 0.75% during the latest week.
- Drivers
Aluminum prices initially moved higher before facing some downward pressure. Market participants remained cautious ahead of the upcoming holidays, and the earlier price increase resulted in some pullback. - Outlook (next month)
Improving market sentiment and industry support could keep aluminum prices firm, with moderate upward movement possible during October.
Paper for Color Boxes (157 g, Double-Coated) – Monthly Change: -3.01%
The tracked price of double-coated paper used for color boxes declined during September, including a further 0.88% decrease during the latest week.
- Drivers
Paper manufacturers continue to face profit pressure, and some production lines have been shut down. Although this may reduce operating rates, inventory pressure remains at some paper companies. Purchasing activity from downstream companies also slowed ahead of the Mid-Autumn Festival. - Outlook (next month)
Demand is likely to remain driven mainly by immediate purchasing requirements, with limited scope for substantial price increases. Prices may therefore remain weak or decline slightly during October.
Stainless Steel (304/2B 0.4 mm, Taiyuan) – Monthly Change: -2.42%
Stainless steel prices fell during September but were unchanged during the latest week.
- Drivers
The spot market continued to operate within a relatively narrow range, with 304 cold-rolled stainless steel prices moving both up and down.
Weak demand and reduced transaction activity ahead of the holiday period have weighed on the market. - Outlook (next month)
Cautious purchasing and relatively weak demand could keep stainless steel prices subdued during October, although market conditions may change as buyers return after the holiday period.
Battery Materials (Lithium Cobalt Oxides) – Monthly Change: -11.74%
Battery materials again recorded the largest monthly decline in this update, continuing the downward trend seen over recent months.
Prices declined by another 2.15% during the latest week.
- Drivers
Cathode material prices have generally fallen, while ternary precursor prices have also declined.
Insufficient downstream demand has contributed to the continued reduction in ternary material prices. At the same time, lithium iron phosphate (LFP) continues to increase its share of the battery market. - Outlook (next month)
Unless downstream demand improves, current market conditions are likely to continue placing downward pressure on ternary battery material prices during October.
What stands out this month?
September’s figures again demonstrate why it is difficult to make broad statements about “raw material prices” in China.
Silicone continued its recent rebound and is now around 32% above its September 2025 level. Copper is almost 39% higher year-on-year, while aluminum alloy, zinc alloy, and ABS are also noticeably above their levels a year ago.
Battery materials tell a very different story. Lithium cobalt oxide costs have now fallen substantially from their early-2026 highs, with September bringing another 11.7% monthly decline. Packaging paper and stainless steel also moved lower during the month.
For importers, this distinction is important when reviewing supplier quotations. If a supplier says that “material prices have increased,” it is worth checking which materials actually make up your product’s BOM and whether their prices have genuinely moved in the same direction.
How to combat rising costs?
Explore cost-reducing tips in this post: Rising Raw Material Prices: What Strategy To Follow? (6 Approaches).
What to do if your Chinese supplier suddenly tells you that material costs have risen: How To Cooperate With Your Chinese Supplier, Part 16: Bad News from China, Raw Material Prices Just Increased!
If your supplier just isn’t working out, maybe sourcing a new supplier will help you find one who can offer you better prices and more. If so, there’s no need to fear switching from your current supplier to a new one if you’re prepared: How To Switch To A Newer, Better Chinese Manufacturer? [eBook].
We hope this is helpful. Our mission at Sofeast is to provide importers with transparency in their supply chain and to give them greater control. And this information is crucial for gaining visibility into your manufacturer’s costing.
By the way, you can always contact us if you have any questions about whether a manufacturer’s quote is reasonable or not.